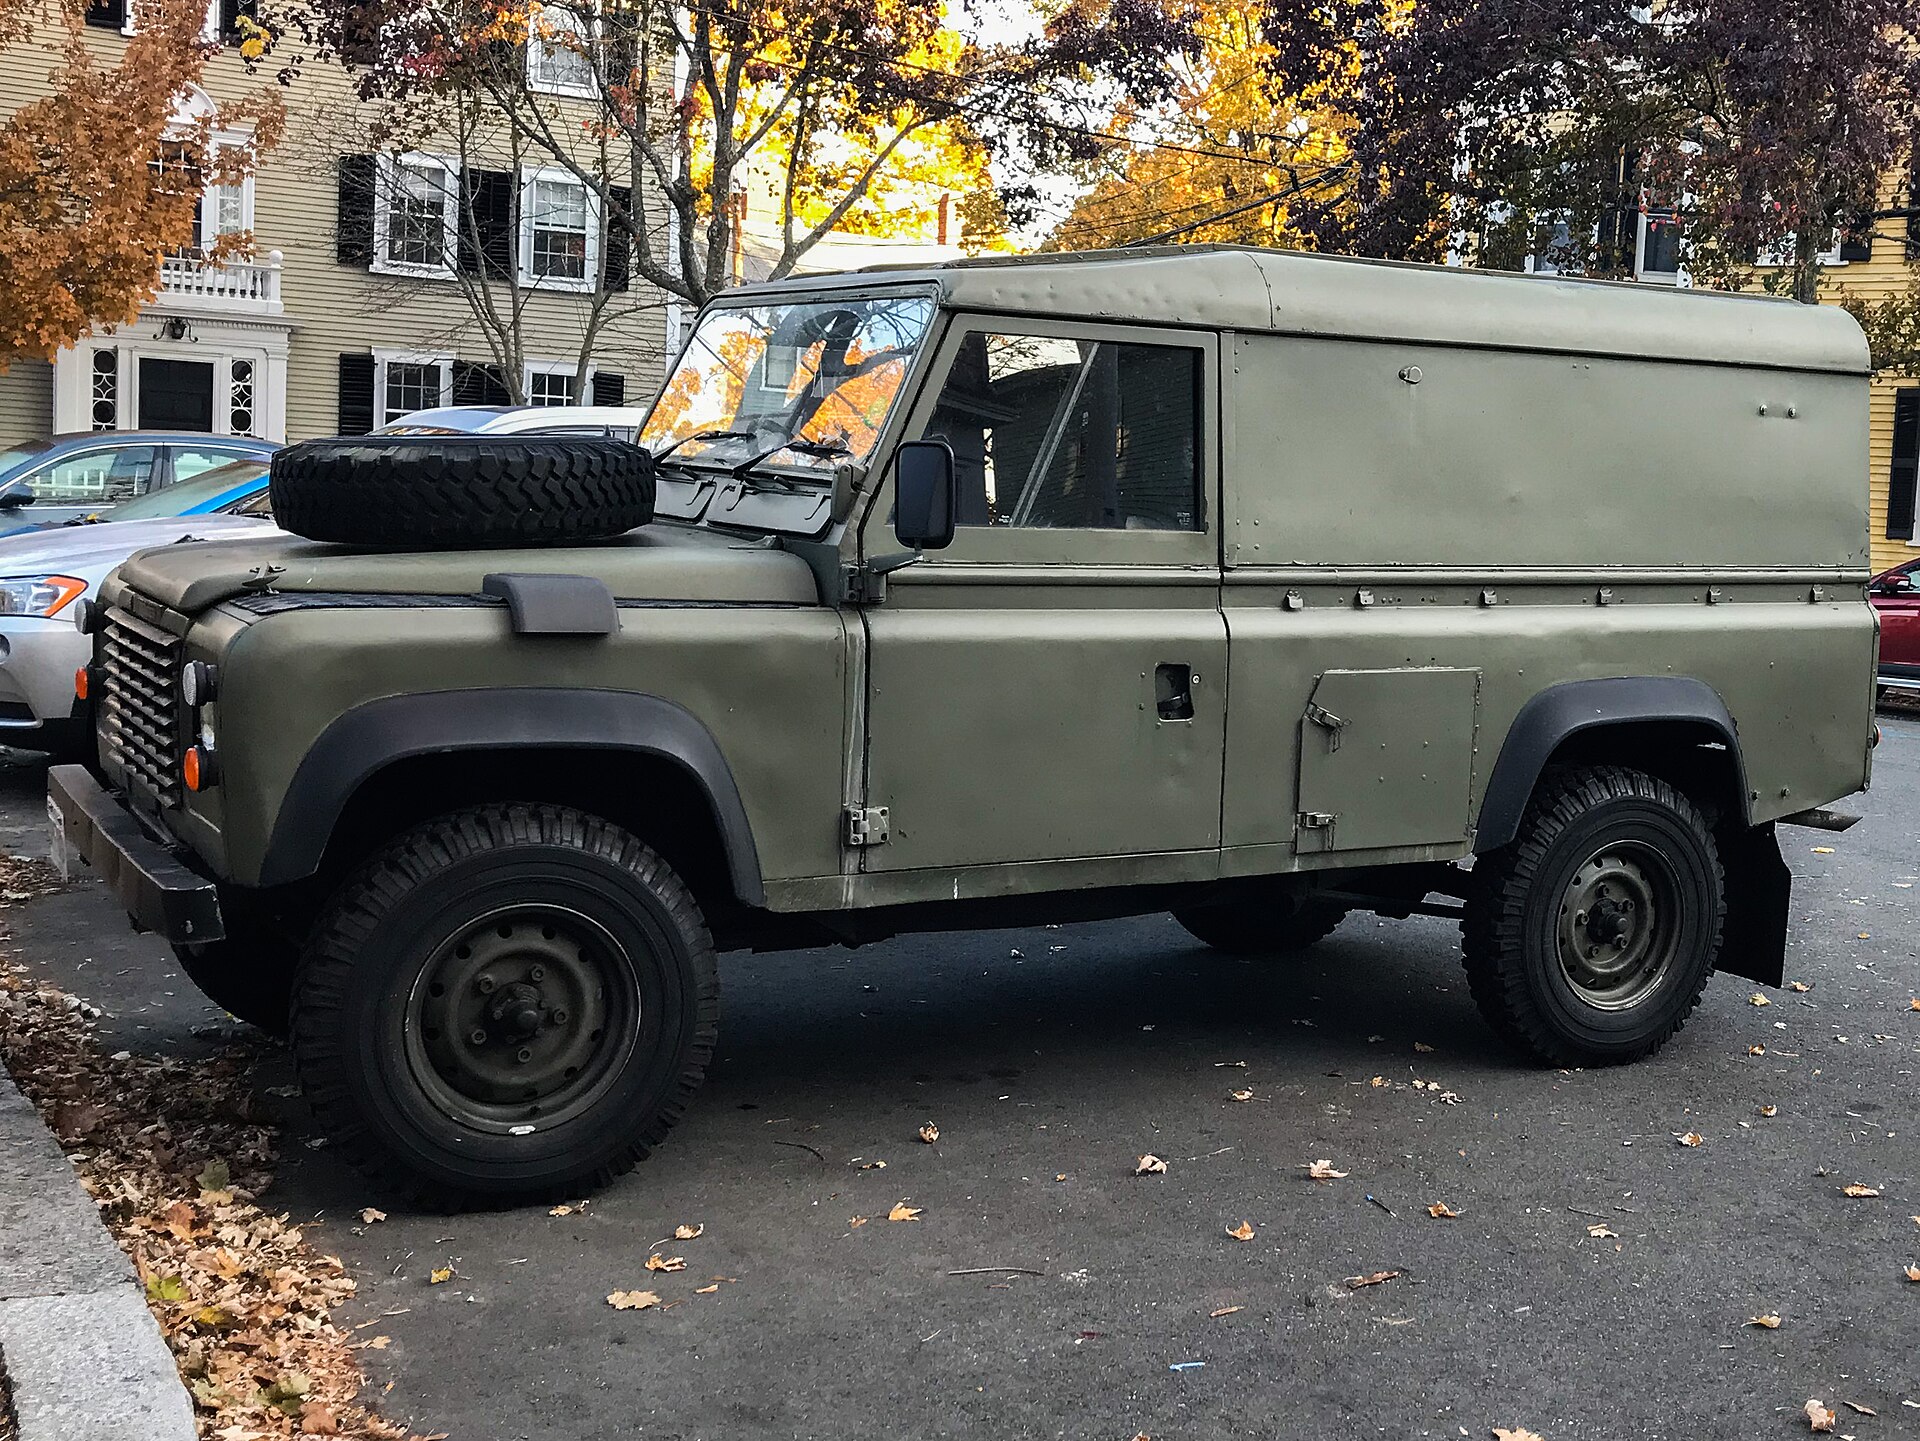
Photo: Fletcher via Wikimedia Commons, CC BY 4.0
Automakers bury their biggest decisions in dull documents. JLR’s August quarterly update read like every other quarter this year — revenue down, margin thin, suppliers misbehaving — and then, a few bullets into the business highlights, the company put it in writing: the Stellantis deal covers “new products for the Defender brand specifically designed for the US market.”
That one clause does more work than any grainy spy shot. It names the brand, the customer and the partner, and the partner happens to own the American assembly complex that already builds Jeep’s only midsize pickup. Everything else circulating right now is inference. Some of it is good inference. None of it is confirmation.
What’s signed, and what very much isn’t
The memorandum of understanding is dated 20 May 2026, and both sides published the same carefully hedged language: non-binding, exploratory, limited to product and technology development in the United States, with anything real contingent on definitive agreements that do not yet exist. Stellantis boss Antonio Filosa talked about complementary strengths. JLR chief executive PB Balaji talked about long-term growth in the US. Neither executive said pickup, truck, plant or 2028.
JLR’s June investor update is where the ambition gets specific. The Defender brand is three vehicles — 90, 110 and 130 — all built at Nitra in Slovakia, and it is the company’s best seller. JLR told investors Defender is the brand assigned to carry American growth, that it is studying new high-potential segments for the nameplate, and that the long-run aspiration is for the US business alone to eventually match the size of all of JLR as it exists today. Nobody promises that and then ships one more trim level.
The duty line that decides the shape of the vehicle
Here is the part that actually governs the engineering. US customs does not care about vibes, it cares about classification. Passenger vehicles arrive under a 2.5 percent most-favoured-nation rate. Cargo-carrying vehicles under five metric tons land in tariff heading 8704, where the general rate is 25 percent. That tenfold gap traces back to the mid-1960s, when Washington hit back at European duties on American poultry, and six decades of trade negotiation later the line is still sitting there untouched.
JLR has already shown shareholders what tariff arithmetic does to a P&L. Its own filings put the all-in rate on EU-built vehicles shipped to the US at 27.5 percent before the 2025 framework cut it to 15, and the UK-built rate dropping from 27.5 percent to 10 under a quota capped at 100,000 vehicles a year. Those are car numbers. A Defender with an open bed behind the cab is not a car, and no framework has trimmed the truck line.
Which is why a Slovakia-built Defender pickup is dead as a business case and a US-built one is not. We walked through the same arithmetic when Volkswagen was weighing an American pickup of its own, and the conclusion does not change because the badge is British.
Toledo already has the open slot
Stellantis published its half of this story last October, months before the MOU existed. The 13 billion dollar, four-year US plan promises roughly 50 percent more American output, five new vehicles and 19 product actions, and it includes nearly 400 million dollars to move an all-new midsize truck program out of Belvidere and into the Toledo Assembly Complex, where the Wrangler and Gladiator are already built, with launch timing in 2028 and more than 900 jobs attached.
That is the only midsize truck line Stellantis is actively spending money on, and it arrives exactly when a partnership product would need somewhere to live. Read the footnote, though: Stellantis states that the investments depend on negotiating development packages with state and local governments. Product plans that ride on tax incentives are product plans that can move again. Ford, meanwhile, is coming at the same segment from the opposite direction with a Bronco-based bed of its own, so the SUV-turned-truck aisle is about to get crowded.
The engineering problem nobody has solved out loud
The current Defender rides on D7x, an aluminium monocoque JLR engineered specifically for it and builds only at Nitra, a plant that needed a third shift added in 2023 just to keep pace with demand. Monocoques hate having their rear structure removed. Delete the roof, rear glass and load floor to make room for a bed and you delete the closed ring that gives the body its torsional stiffness. You buy that stiffness back with heavy reinforcement, a bolted-in bed subframe, or by giving up on the unibody entirely.
So there are two honest outcomes here, and they are not the same vehicle. Option one is a monocoque Defender pickup that still drives like a Defender, tows respectably, hauls a modest payload, and costs a small fortune to fix when somebody reverses into the bedside, because aluminium bodywork means bonded and riveted repairs at certified shops rather than an afternoon with a hammer and a heat gun. Option two is Defender sheet metal on the Toledo truck architecture: genuine payload, a frame that can be measured and pulled straight, cheap collision parts, and chassis DNA that started life at Jeep.
Neither option is shameful, and both have precedent in this industry. But it clarifies the question enthusiasts should actually be asking: is a Defender defined by how it is built or by what is stamped on the tailgate? If it is the former, the platform disclosure will matter far more than the horsepower figure. And if the answer shows up on a ladder frame, ask about frame coatings and water drainage before you sign anything, because Wrangler and Gladiator owners have already had that conversation.
JLR needs this more than Stellantis does
The financial backdrop is not decoration. JLR’s most recent quarter produced 6.0 billion pounds of revenue, down 9.6 percent year on year, 109 million pounds of pre-tax profit before exceptional items, down nearly 69 percent, a 2.8 percent adjusted EBIT margin and negative 998 million pounds of free cash flow. The company is chasing 1.7 billion pounds of cost savings to drag its breakeven volume down toward 300,000 vehicles, and Range Rover, Range Rover Sport and Defender together made up 80.8 percent of wholesale volume.
That last figure is the real story. Four-fifths of a luxury automaker’s output leans on three nameplates, one of which is simultaneously being asked to carry the brand’s electric future while Range Rover launches its first EV into the company’s roughest financial stretch in years. Renting somebody else’s American factory floor is a comparatively cheap way to add a model line without adding a plant, which is exactly why this idea exists at all.
What to watch, and what to do about it
- Timing: MOU first, binding agreements second, tooling third. Anything shaped like a Defender truck realistically lines up with Toledo’s 2028 window at the earliest, so shop the 130 that already exists rather than waiting.
- Price: a US-assembled truck skips the 25 percent duty entirely, which is how it could undercut an imported Defender. Current owners should assume any price gap pressures residuals on the big-body cars first.
- Service: if Stellantis builds it, ask who administers the warranty and where the nearest certified aluminium body shop sits. Insurers price body material and sensor recalibration labour, not badges.
- Paper trail: definitive agreements, Ohio incentive filings, EPA certification data and plant codes in new VIN structures will all surface before any reveal. The documents always talk first.
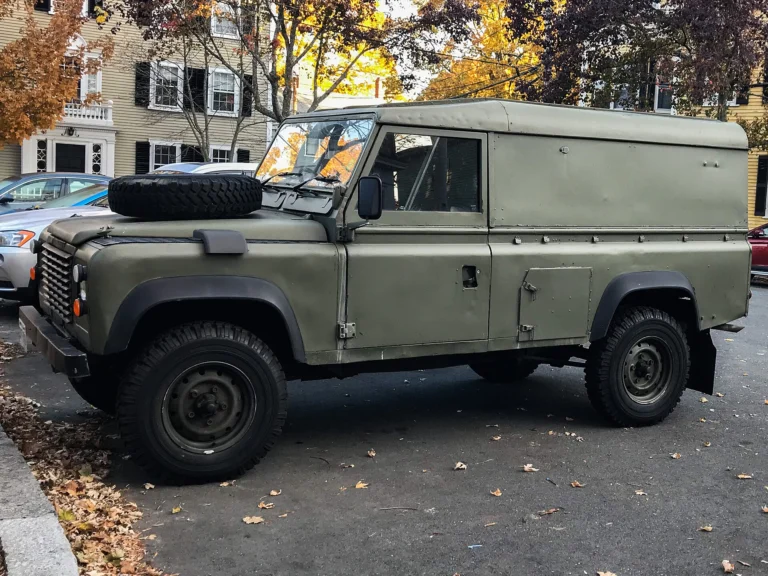
Land Rover building a truck again is not the interesting part. It built them for decades, and the last of the original Defenders left Solihull in 2016. The interesting part is whether JLR can borrow Stellantis’s frames, floor space and tariff address without borrowing the parts of the recipe that made the Defender worth the money in the first place.
About the Author