Most racing news starts at a track. This story starts at a clerk’s desk in Miami.
On September 16, 2026, a new case landed on the U.S. District Court for the Southern District of Florida’s public civil filing index: Rosner v. Delaware Life Insurance Company et al., case number 1:26-cv-26388-DPG, assigned to Judge Gayles. The court classified it as nature of suit 190, “Contract: Other,” with jurisdiction claimed under 28 U.S.C. § 1332, federal diversity jurisdiction.
That’s a dry line in a list that also includes cruise-ship injury claims, trademark cases and immigration petitions. It matters to motorsport because of who sits behind Delaware Life, and who runs the company that owns part of Formula 1’s newest team.
Follow the org chart, not the headlines
Here is the chain, built only from the companies’ own documents.
Delaware Life belongs to Group 1001, an insurance holding company. Group 1001 says that as of December 31, 2025, it had combined assets under management of $81.6 billion and more than 496,000 active annuity contracts and life insurance policies. Its brands include Delaware Life, Gainbridge and Clear Spring Life and Annuity Company. The same page says Group 1001’s strategic partnerships connect people “through education and sports,” which is corporate-speak for writing big checks to teams and leagues.
Related Articles
- Porsche Licensed an 80-Percent 550 Spyder That Runs on 48 Volts — and Can’t Legally Touch a Road
- Tom Cruise Patted Kyle Busch’s Empty Chair at Daytona — and NASCAR Had More Tributes Where That Came From
Group 1001’s own releases have identified Dan Towriss as its CEO and president. Now go to General Motors’ newsroom. When the FIA and Formula One Management approved the Cadillac entry in March 2025, GM’s release said the team was backed by TWG Motorsports and GM. It also quoted Dan Towriss as CEO of TWG Motorsports. The release describes TWG Motorsports as the motorsports entity of TWG Global, which also owns Andretti Global, Spire Motorsports and Wayne Taylor Racing.
So the executive who has led the insurance group whose subsidiary is now a named federal defendant also led the racing arm that brought Cadillac into F1. That doesn’t prove wrongdoing by anyone. It does explain why a Florida contract dispute about an annuity is suddenly a paddock story.
What the court record shows, and what it doesn’t
The public index gives the case caption, filing date, judge, nature of suit and jurisdictional basis. It does not list every defendant; everyone beyond Delaware Life is covered by “et al.” It does not reproduce the complaint’s allegations. We could not obtain the complaint itself through public channels before publication, so this article doesn’t repeat claims about its contents that we couldn’t verify against the filing. That means no dollar figures, no count list and no characterization of what the plaintiff says happened.
That caution isn’t pedantry. A civil complaint is one side’s version of events, written by lawyers whose job is to make it sound as damaging as possible. Nothing in it is a finding. No court has ruled on anything in this case, and at this stage, no defendant has had to prove anything.
Reading the legal plumbing
The jurisdictional code on the index tells you something about the case’s structure.
Section 1332 generally puts cases in federal court when the parties are citizens of different states and more than $75,000 is at stake. There is also a class-action track in subsection (d), added by the Class Action Fairness Act. Under it, federal courts can hear class actions where the combined claims exceed $5 million and at least one class member is from a different state than any defendant. That track doesn’t apply if the proposed class has fewer than 100 members, and individual class members’ claims are added together to reach the $5 million threshold.
Why does that matter? If this case proceeds as a class action on behalf of annuity holders, the stakes won’t be one retiree’s contract. They’ll be the combined claims of everyone the plaintiff says was in the same position. Before that happens, though, the plaintiff has to clear two hurdles. First, the case has to survive the defendants’ expected motions to dismiss. Second, a judge has to certify a class. Many proposed class actions never get past one of those two stages. Filing is the easy part.
So what does this mean for the Cadillac team?
On the grid, nothing changes this weekend. A civil contract suit against an insurance company doesn’t touch a race team’s cars, contracts, staff or FIA entry.
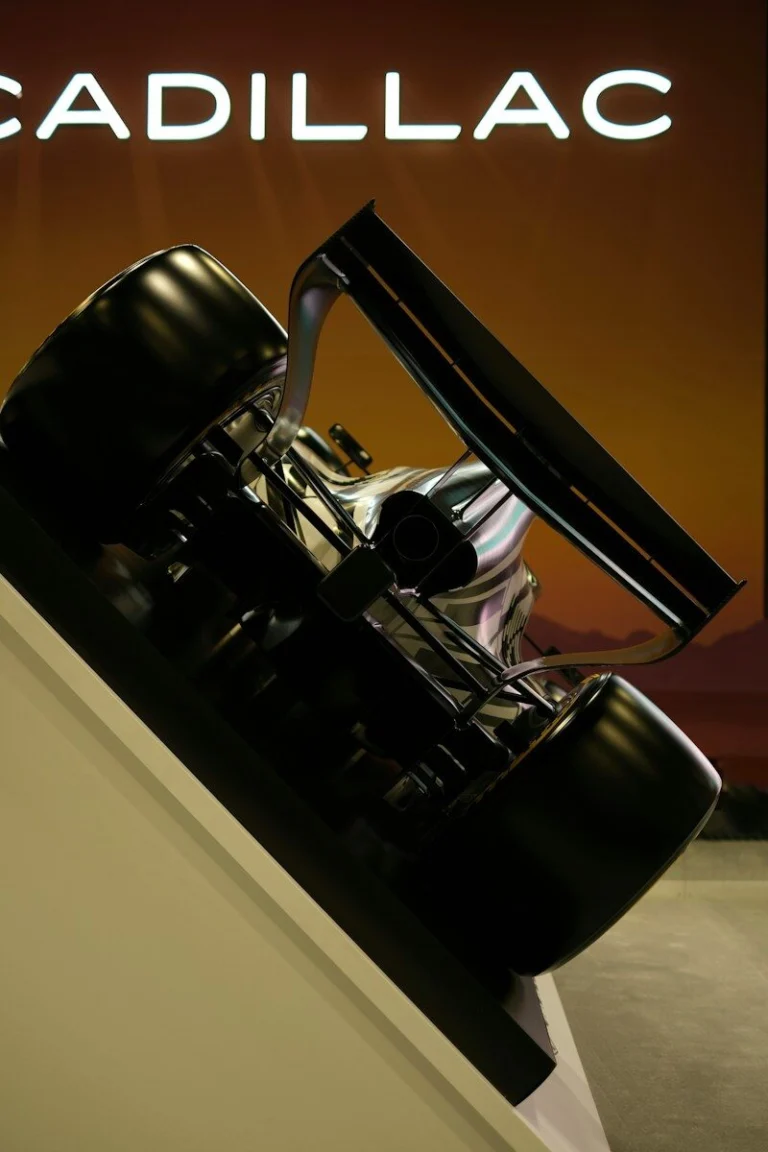
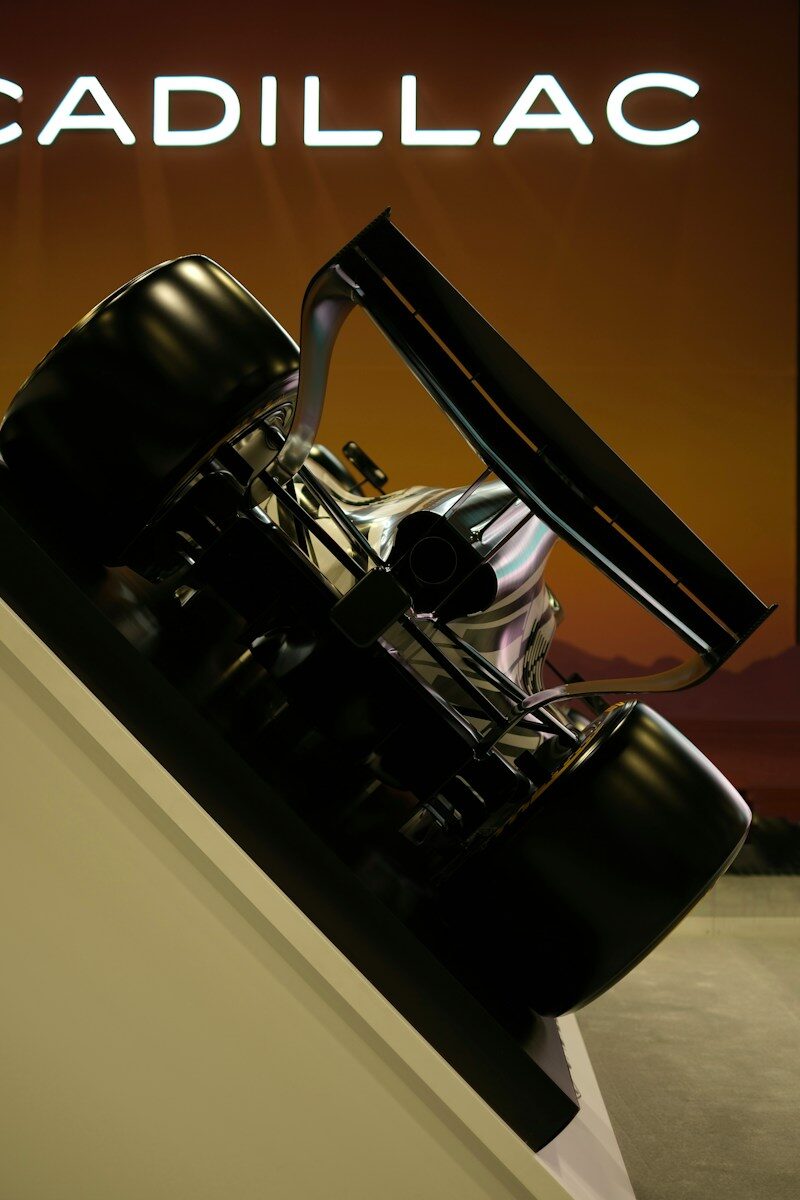
The questions worth asking are about money over the longer term, because Cadillac’s F1 program is not a cheap entry. GM’s release describes more than 300 people working on aerodynamics, chassis, software and vehicle dynamics. It lists operations in Indianapolis, Charlotte, Warren and Silverstone. It also announces a separate company, TWG GM Performance Power Units LLC, led by Russ O’Blenes, meant to set Cadillac on the path to becoming a “full works” team building its own chassis and power units.
A full-works F1 program is a multi-year spending commitment. Even the best-run teams depend on owners who can keep funding it through bad seasons and outside pressure. When the parent company’s broader business faces legal scrutiny, the risk to a team usually isn’t a sudden collapse. It’s slower and quieter: more cautious budgets, a partner rethinking its level of commitment, or a change in ownership structure. Watch for those signals rather than for dramatic headlines.
GM is the other factor. Its name is on the power-unit company, and its brand is on the car. If the ownership picture around TWG changes, the relationship between the two partners becomes the thing to watch. So far, nothing in GM’s public record suggests any change.
If you own a Delaware Life annuity
This is where the story stops being about racing. Delaware Life’s own product disclosures state that its guarantees are backed by the financial strength and claims-paying ability of Delaware Life Insurance Company of Waltham, Massachusetts. That’s standard language for annuities, and it’s the part owners should take seriously. An annuity guarantee is only as good as the insurer behind it.
Related Articles
- The Freeway Revolts of the 1960s Still Dictate How America Builds Roads Today
- BRM’s One-of-One Le Mans Prototype Just Got Its Roof and V12 Back After 30 Years
Practical steps for owners: pull out your contract and note its surrender schedule and any free-look period that may still apply. Before you move money, check the current financial-strength ratings from the major rating agencies. Don’t surrender a contract in a panic. Surrender charges can easily cost more than the risk you’re trying to avoid, and a lawsuit filing by itself says nothing about whether the insurer can pay its claims. If you’re unsure, talk to a fee-only adviser who doesn’t earn a commission for moving you into a different product.
If you just want to buy a Cadillac
Relax. The CT5 on the dealer lot is a General Motors product. GM’s own description of the company lists Cadillac among brands it builds and sells, alongside Buick, Chevrolet and GMC. Your warranty, recalls, parts and service come from GM and its dealers, not from any F1 ownership group. What happens in a Miami courtroom won’t change what happens at your service department.
What to watch next
The docket will tell the real story. Watch for the full defendant list, motions to dismiss, any motion for class certification and any request to consolidate this case with related filings elsewhere. If a judge certifies a class, the case becomes much bigger. If it’s dismissed early, it becomes a footnote. Either way, for Cadillac’s F1 program, the numbers that matter will show up in the owners’ funding decisions long before they show up on a timing screen.
About the Author