Jody Scheckter won the 1979 Formula 1 World Championship in a Ferrari, and he’s still the last Ferrari driver to take the drivers’ title before Michael Schumacher ended the team’s 21-year wait in 2000. He’s also the only South African driver to ever win an F1 championship. What he did with the money and the decades after climbing out of the cockpit turned out to be a far messier story than anything that happens when a modern Ferrari rolls out of Maranello wearing a champion’s number, and a UK tax tribunal just spent 85 pages explaining exactly why.
The First-tier Tribunal’s Tax Chamber ruled on September 3, 2026 that Scheckter cannot claim roughly £1.46 million in what’s called “sideways loss relief,” tied to years of losses generated by Laverstoke Park, the organic buffalo, dairy and abattoir operation he built in Hampshire. The case, Jody Scheckter v The Commissioners for HMRC, runs 292 numbered paragraphs, and it’s a rare tax judgment that spends real time being sympathetic to the man losing it. HMRC’s side alone was argued by a King’s Counsel, which tells you how seriously the taxman took getting this money back.
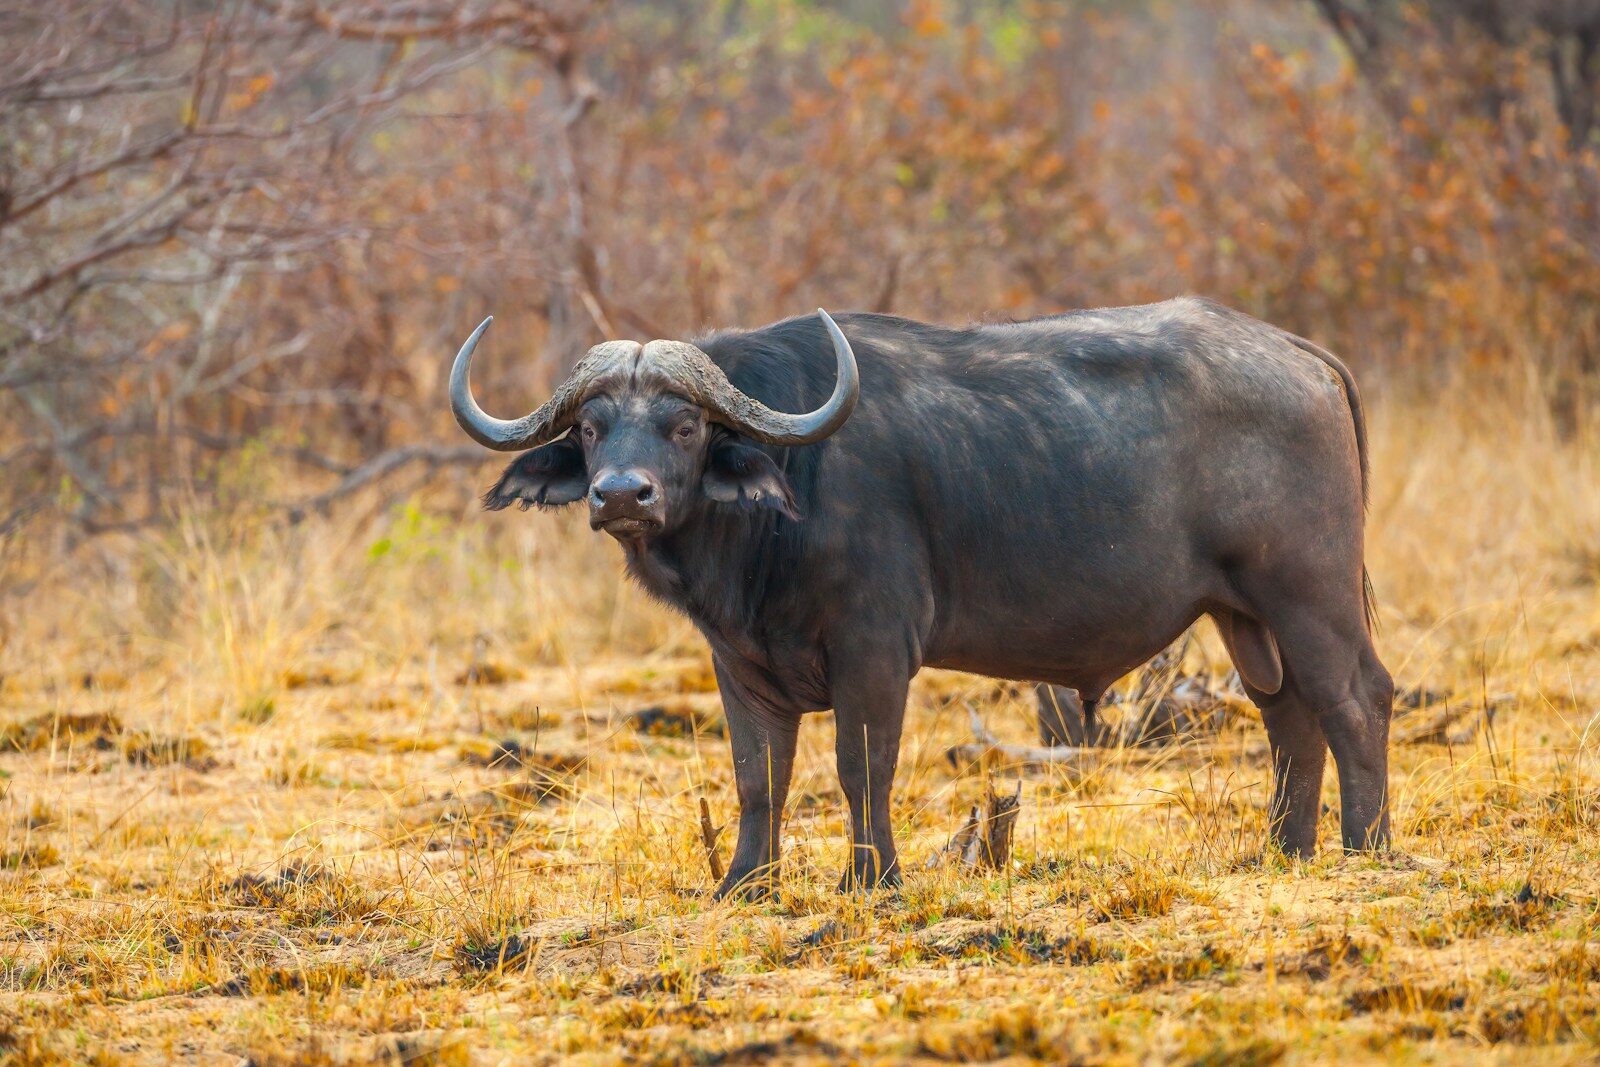
Most coverage of the ruling skipped how Scheckter ended up running a buffalo farm in the first place. After retiring from racing in 1980, he founded FATS Inc., a company that built firearms training simulators, and sold it for a substantial gain. That sale funded the next act. In 1996 he relocated to England with his wife, Clare, bought Laverstoke Park and its surrounding 530 acres in Hampshire, and by 2001 had incorporated Laverstoke Park Produce LLP, in which he held a 99% stake.
What followed was not a hobby farm. Over the next decade, the LLP built a multi-species abattoir, a boning hall, a retail packing plant, a charcuterie facility, a curing facility, a dairy processing unit, a mozzarella facility and an ice cream production line, spread across more than 3,000 leased acres in Hampshire and Wiltshire by 2009. Staffing grew from 42 employees in 2006 to 135 by 2010. Scheckter trademarked the operation with the tagline “the biggest small-holding in the world,” sold milk to Waitrose, hosted the Hampshire Food Festival and the British BBQ Championships, and ran an on-site laboratory to test soil and produce. Tribunal records show he put just under £55 million of his own capital into the LLP between 2003 and 2013.
None of it made money in any consistent way. According to the tribunal’s findings, the LLP posted a loss in every accounting period from its founding through the year ending March 2018, turned a rare profit the following year, then went straight back to losing money through 2025.
That’s where the tax dispute starts. Across the tax years ending in 2008, 2009 and 2010, the LLP’s trading losses totaled roughly £13.3 million, and Scheckter claimed close to £3.8 million of that as sideways loss relief against his other personal income and capital gains, a legal mechanism that lets partners in a trading partnership set the partnership’s losses against income earned elsewhere. It’s a common structuring tool for capital-intensive ventures. HMRC opened enquiries into those returns as early as 2010 but didn’t issue closure notices formally denying the relief until January 2019, nine years later, assessing roughly £1.46 million in additional income tax. Scheckter appealed, and the case wasn’t heard until June and July of 2026. A dispute over three tax years from the late 2000s took roughly a decade and a half to resolve, which is worth remembering if you’ve ever assumed HMRC forgets about an aggressive filing position. It doesn’t, and the interest meter doesn’t stop running while it thinks it over.
The legal fight turned on two provisions of the Income Tax Act 2007 written specifically to stop wealthy taxpayers from writing off “hobby farming” losses against their salaries. Section 67 blocks sideways relief once a farming trade has posted losses for five straight years, unless that farming activity is merely “ancillary” to a larger, genuinely commercial business. Section 66 separately requires that the trade be run “on a commercial basis” with a real view to profit. Scheckter’s counsel argued the farming operation was one piece of a bigger, structurally sound enterprise that also included the abattoir company; HMRC argued the whole venture was a loss-generating passion project with an expensive brand attached.
Judge Tony Beare’s tribunal split the difference in a strikingly granular way. It agreed the farming trade was part of a larger trading undertaking, and even agreed that undertaking was being run with a genuine eye toward eventual profit. But it found the farming operation wasn’t merely “ancillary” to that larger business, it was the core of it, not a supporting act, which knocked out Scheckter’s main escape route under Section 67. Separately, the judges concluded the farming trade itself wasn’t being run “on a commercial basis” during the years in question, which sank the claim under Section 66 too. Appeal dismissed on every point that mattered.
What makes the ruling worth reading beyond the numbers is paragraph 291, where the tribunal drops the usual dry procedural tone. Judge Beare wrote that it was “impossible” to sit through the case “without feeling considerable sadness” at how a project “conceived with such imagination and originality” had turned out, and found that Scheckter, while genuinely motivated by profit, also had an “altruistic purpose” in trying to build a model for organic farming. It’s the kind of line you almost never see in a tax judgment, and a reminder that tribunal disputes are rarely as simple as villain versus victim.
Scheckter isn’t the only figure from Formula 1’s world to get tangled up in paperwork this year. Bernie Ecclestone ran into his own document problem in Portugal within the same stretch of months, tripped up by a single piece of paperwork he apparently never carries.
For anyone running a passion project alongside money made in a first career, restoration shops, boutique manufacturers, even a race team bankrolled by outside income, the practical lesson sits inside the tribunal’s reasoning. Sideways loss relief isn’t automatically available just because a venture loses money for a good reason. Tax authorities and tribunals look hard at whether a labor of love is actually run like a business, with pricing, staffing and expansion decisions driven by commercial logic rather than ambition. Racing’s own governing body applies a similar standard to results on track: the FIA leaned on its own fine print to strip Pierre Gasly of a Monaco podium finish twice within three months this yar, proof that in motorsport and in tax law alike, the paperwork behind a decision can matter as much as the decision itself.
Scheckter has 56 days from the release of the decision to seek permission to appeal.
Your Turn: Ever seen a passion project turn into a tax headache? Share your story in the comments.
About the Author